TEAM GOODSON | ORMOND BEACH REAL ESTATE
Good questions deserve
thoughtful answers.
Whether you're buying your first Florida home, considering a move to the coast, or preparing to sell, there's a lot to think about. We've gathered answers to some of the questions we hear most often.
Every property and every situation is different. Our goal is to help you understand your options, ask the right questions, and make decisions that feel right for you.
GETTING TO KNOW US
Working With Team Goodson
Who is Team Goodson?
We're Amy and Mark Goodson, a husband-and-wife real estate team with Adams, Cameron & Co., Realtors. We live beachside in Ormond Beach and have been helping buyers and sellers since 2017. We work together to guide our clients from the first conversation through closing and beyond.
What areas do you serve?
Our home base is Ormond Beach, and we help clients throughout the surrounding area, including Ormond by the Sea, Daytona Beach, Port Orange, Ponce Inlet, Flagler Beach, and Palm Coast. We especially love helping people discover the different lifestyles available along Florida's northeast coast.
Do you specialize in a particular type of property?
Beachside and waterfront properties are a big part of what we do, but we help buyers and sellers with all kinds of homes. From oceanfront condos and riverfront properties to established neighborhoods and new construction, our focus is on finding the right fit for each client.
What makes Team Goodson different?
We believe good real estate advice starts with listening. We're honest about what we see, even when it isn't necessarily what someone hoped to hear. We help our clients navigate the details, solve problems, and make informed decisions without pressure. Our goal isn't just a successful closing. It's earning your trust and friendship long after the transaction is complete.
How do I get started?
Just give us a call, send a text, or reach out through our website. We'll start with a conversation about what you're hoping to accomplish, your timeline, and any questions you have. Whether you're ready to make a move or simply exploring your options, we're happy to help.
FOR HOME BUYERS
Buying a Home in Florida
How do I know if I'm ready to buy?
You don't need to have everything figured out before starting the conversation. We'll talk about your goals, timeline, lifestyle, and budget. A lender can help you understand your financing options and what monthly payment feels comfortable for you.
Do I need to be preapproved before looking at homes?
Not necessarily, but we strongly recommend speaking with a lender early. Preapproval helps establish a realistic price range and can strengthen your offer. If you're purchasing with cash, we'll discuss the documentation sellers may request to verify available funds.
Do I need my own Realtor when buying a home?
Having your own representation means having someone focused on your interests throughout the purchase. We'll explain how buyer representation works, including any required agreements and how our compensation is handled, before we begin touring homes together.
How long does it take to buy a home?
Once you're under contract, many purchases close in approximately 30 to 60 days, although cash purchases may close sooner and some transactions take longer. The timeline depends on financing, inspections, insurance, title work, and the terms negotiated in your contract.
What costs should I expect beyond the purchase price?
Depending on the property and financing, expenses may include inspections, appraisal fees, lender charges, title and settlement costs, insurance premiums, prepaid property taxes, and HOA or condo fees. We'll help you identify these expenses early so you can consider the full cost of ownership.
Do I need a home inspection?
We strongly recommend having a home inspected, even when purchasing new construction. An inspection can identify concerns that aren't obvious during a showing. Your contract determines the inspection deadlines and what options you have if problems are discovered.
What is earnest money?
Earnest money is a deposit made according to the purchase contract to demonstrate your commitment to the transaction. The amount is negotiable, and the deposit is generally credited toward your purchase at closing. Whether it is refundable if the transaction doesn't close depends on the contract terms and circumstances.
Why is homeowners insurance such an important consideration in Florida?
Insurance availability and cost can vary significantly based on a home's age, roof, construction, location, and other factors. We encourage buyers to obtain insurance quotes early in the process, rather than waiting until just before closing. Flood insurance may also be an important consideration.
What should I know about Florida property taxes and homestead exemptions?
The current owner's property tax bill may not reflect what you'll pay after purchasing. A change in ownership can affect the property's assessed value, and qualifying Florida permanent residents may be eligible for homestead benefits. Eligibility generally depends on owning and using the property as a permanent residence on January 1, with applications typically due by March 1. We recommend confirming your situation and estimated taxes with the county property appraiser.
Is it better to buy new construction or an existing home?
Neither is automatically the better choice. New construction may offer warranties, modern features, and builder incentives, while existing homes may offer established neighborhoods, mature landscaping, or locations that are difficult to duplicate. We help buyers compare the complete picture, including costs, contracts, and long-term value.
COASTAL PROPERTY OWNERSHIP
Florida Condos & Waterfront Living
There's a lot to love about living near the water. There are also some important details worth understanding before you buy.
What should I look at before buying a Florida condo?
In addition to the unit itself, it's important to review the condominium association's financial condition, budget, reserves, insurance, meeting minutes, rules, and any pending or planned assessments. We'll help you identify the documents and questions that deserve attention before you commit to a purchase.
What are milestone inspections and structural integrity reserve studies?
Florida has inspection and reserve-study requirements that apply to certain condominium buildings. Milestone inspections evaluate specified structural conditions, while structural integrity reserve studies help associations plan for the cost of maintaining and replacing major building components. Requirements depend on the building and applicable law, so we encourage buyers to review the association's reports and consult qualified professionals when questions arise.
What is a special assessment?
A special assessment is an additional charge an association may levy to cover expenses beyond its regular operating budget and available reserves. Assessments can relate to repairs, improvements, insurance, or other association obligations. Before buying, it's important to ask about assessments that have been approved, proposed, or discussed, and understand how any existing assessment will be handled in the purchase contract.
Can I rent out my condo when I'm not using it?
Possibly, but rental rules vary significantly by condominium association and location. Some buildings permit short-term rentals, while others require minimum lease periods, limit the number of rentals, or impose approval requirements. We'll help you investigate the applicable restrictions before you purchase rather than assuming a property can be rented whenever you choose.
Do I need flood insurance if I'm buying near the ocean or river?
Flood insurance requirements depend on factors including the property's flood zone and your lender's requirements. Even when flood insurance isn't required by a lender, flooding can still occur. We recommend reviewing flood risk and obtaining quotes early so you understand the potential cost and coverage options.
What should I consider when buying a home with a dock or seawall?
Beyond the house itself, it's worth investigating the condition of the dock and seawall, water depth, tidal conditions, boating access, and any permits or restrictions affecting the waterfront improvements. Specialized inspections and conversations with the appropriate local authorities can help you understand what you're buying and what maintenance may be required.
Is living beachside different from living on the mainland?
It can be. Beachside living offers proximity to the ocean and a distinctive coastal lifestyle, while mainland neighborhoods may offer different lot sizes, amenities, housing options, and access to shopping and services. Property maintenance, insurance, and exposure to coastal conditions can also differ. We'll help you compare the tradeoffs based on how you want to spend your time.
FOR HOME SELLERS
Selling Your Home
Selling a home involves more than putting a sign in the yard. The right strategy begins with understanding your property, your goals, and the buyers you're hoping to attract.
How do I find out what my home is worth?
We provide a complimentary, no-obligation market analysis using recent comparable sales, competing listings, current market conditions, and your home's unique features. We'll explain the reasoning behind our recommended price so you can make an informed decision.
How important is pricing my home correctly?
Pricing is one of the most important decisions you'll make. Buyers compare your home with other available properties, and an unrealistic asking price can limit interest before buyers ever schedule a showing. Our goal is to position your home competitively from the beginning while keeping your financial objectives in mind.
What should I do to prepare my home for sale?
Preparation doesn't always mean expensive renovations. Sometimes cleaning, decluttering, landscaping, and addressing visible maintenance concerns make the biggest difference. We'll walk through your home together and help you prioritize improvements based on what buyers are likely to notice and value.
How do you market a listing?
We develop a marketing strategy around the property and its likely buyers. Depending on the home, that may include professional photography, video, online listing exposure, social media, and the reach of Adams, Cameron & Co., Realtors. We focus on presenting your home's strongest features and reaching the audience most likely to appreciate them.
What if my home isn't getting showings or offers?
We'll look at the available information together, including online interest, showing activity, buyer feedback, competing properties, and recent sales. Sometimes the presentation needs attention. Other times, the market is telling us something about price. We'll discuss what the evidence suggests and recommend adjustments when appropriate.
How long will it take to sell my home?
That depends on the home's price, condition, location, competition, and market conditions. We'll review recent local activity and discuss a realistic expectation, but no agent can guarantee exactly when a home will sell.
What happens after I accept an offer?
Once you're under contract, there may be inspections, financing and appraisal requirements, title work, and other deadlines to manage. We'll help coordinate communication among the parties, monitor contractual milestones, and guide you through the steps toward closing.
What closing costs should I expect as a seller?
Seller expenses may include negotiated real estate compensation, title and settlement charges, documentary stamp taxes, property tax prorations, and other costs depending on the contract. We'll prepare an estimated seller net sheet so you can understand your potential proceeds before making decisions.
GETTING TO KNOW THE AREA
Living in Ormond Beach
One of our favorite parts of this business is helping people discover the community we call home.
What should I know about relocating to Florida?
Florida offers year-round opportunities to enjoy the outdoors and has no individual state income tax. But relocating also means understanding things like homeowners insurance, property taxes, hurricane preparedness, and the differences between neighborhoods. We'll help you get familiar with the area and connect you with appropriate professionals when you need specialized advice.
Why should I consider Ormond Beach?
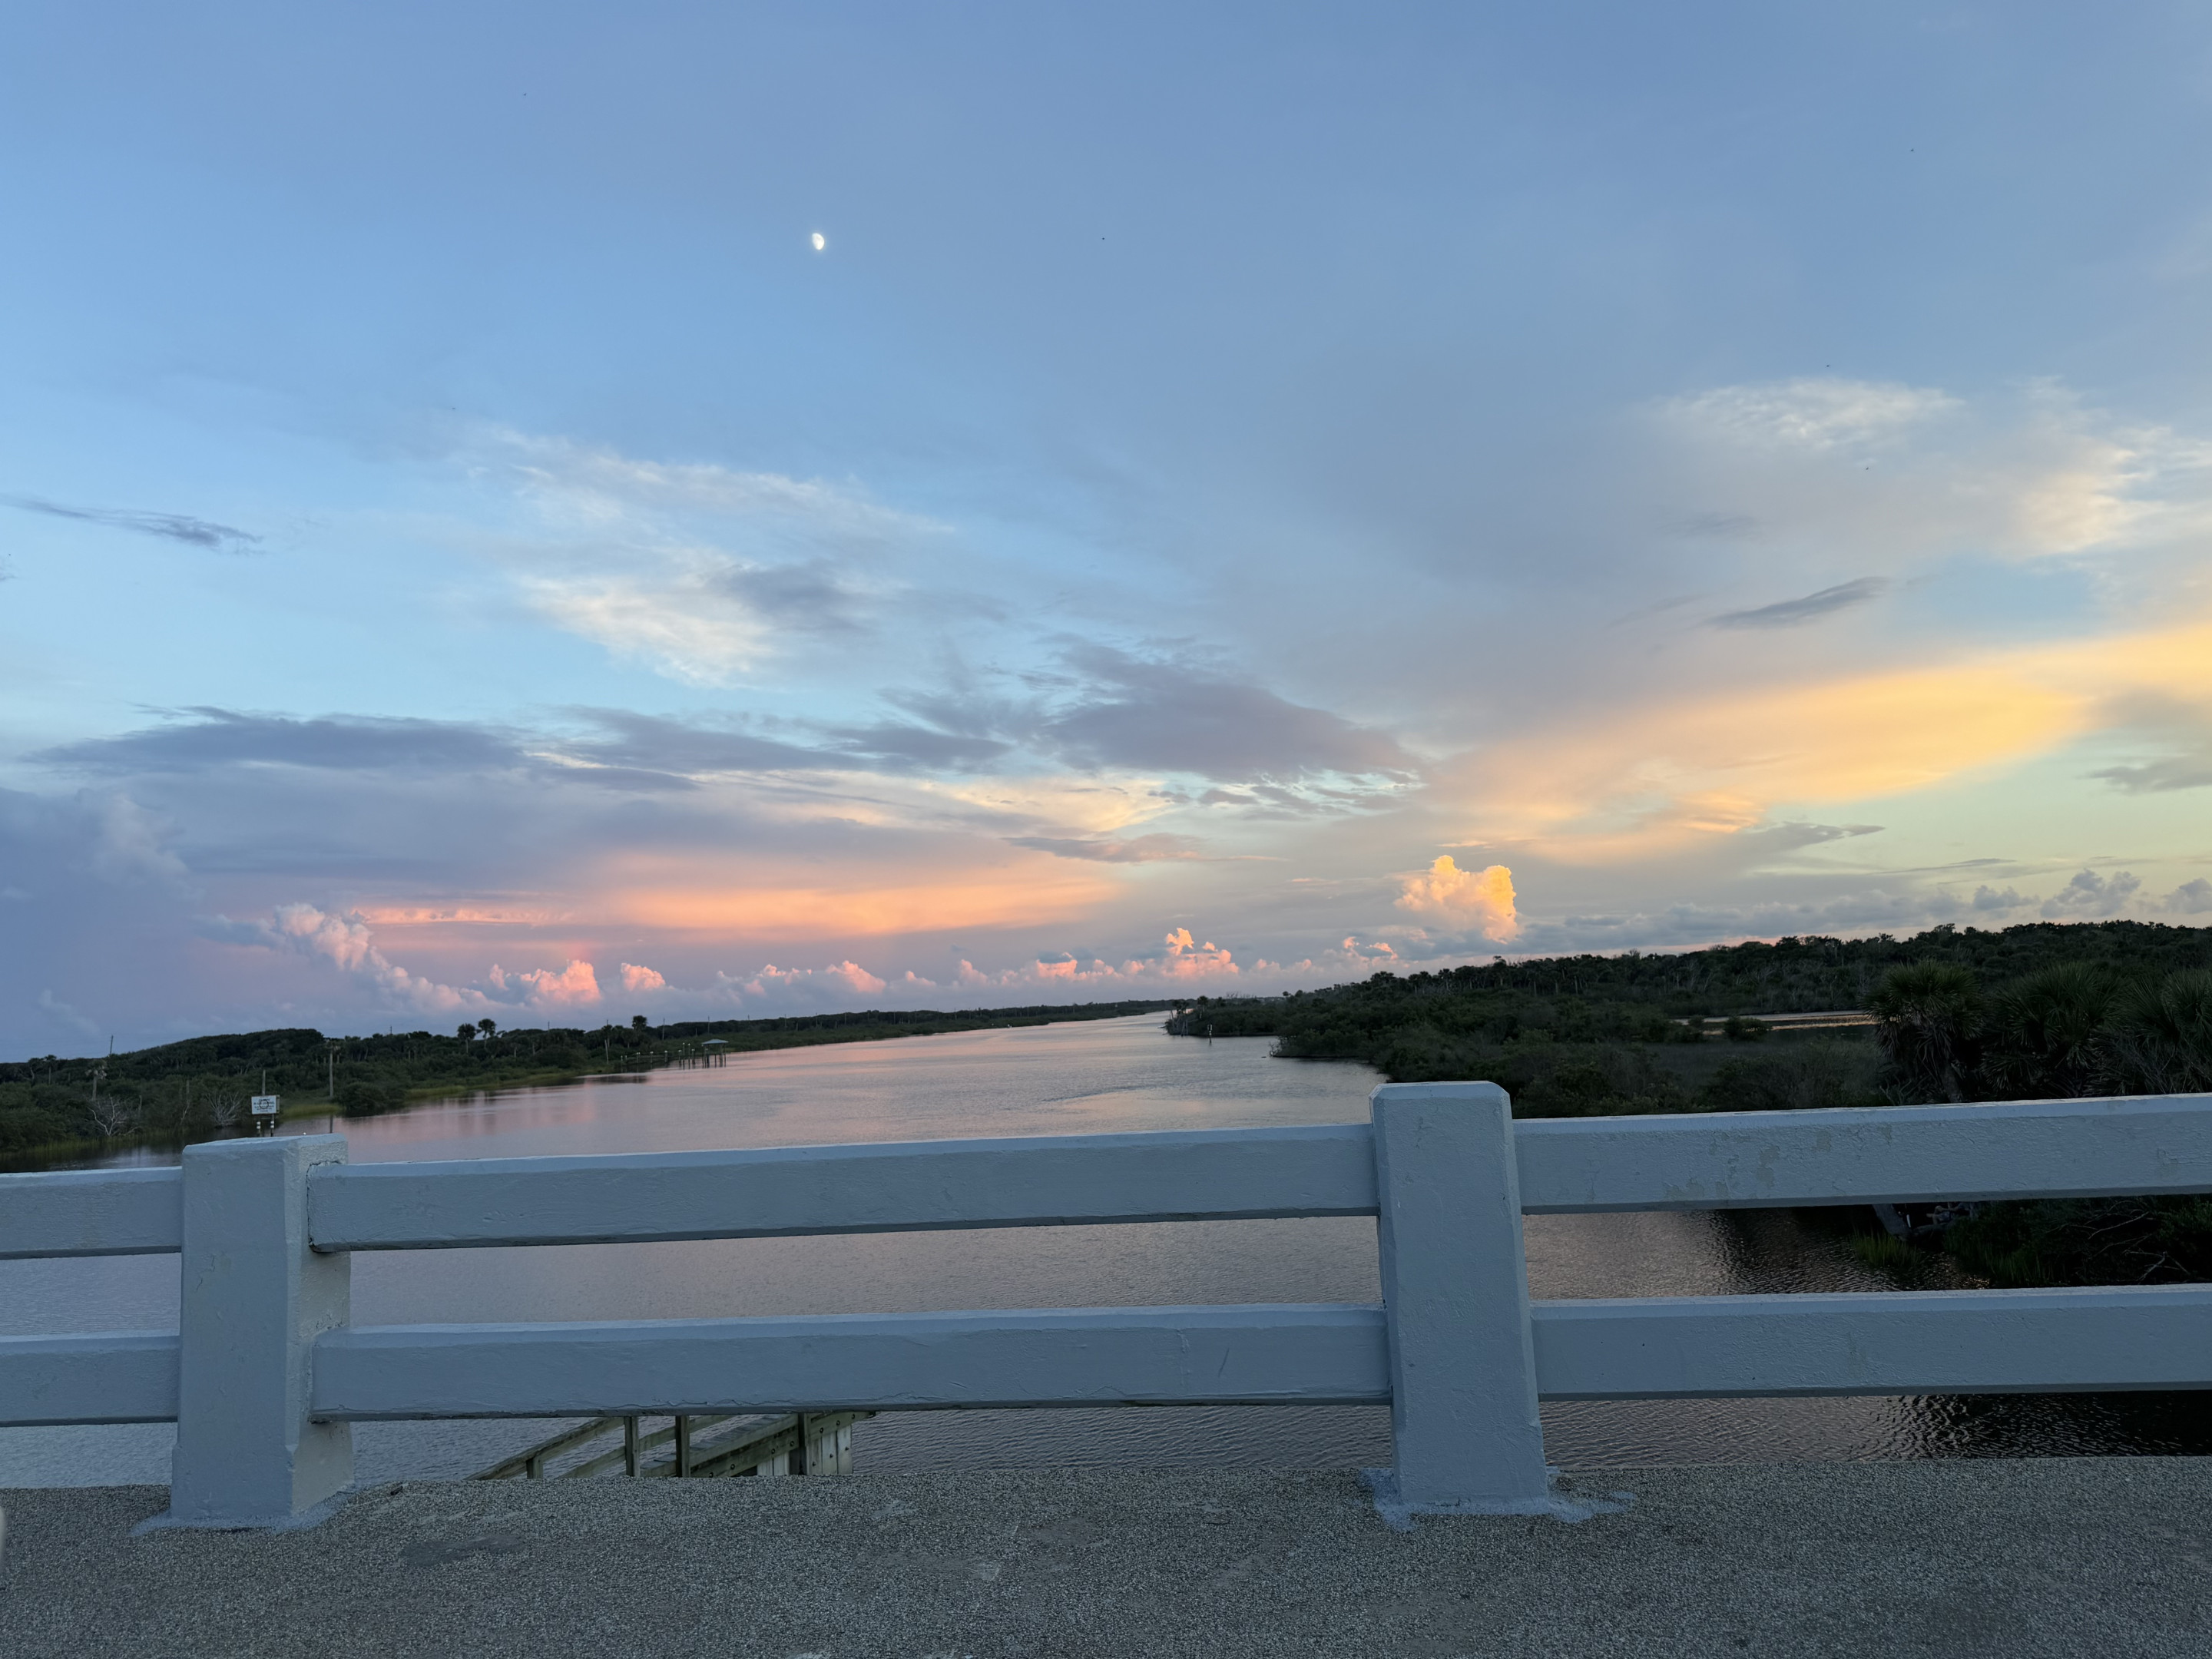
We fell in love with Ormond Beach for its beautiful coastline, established neighborhoods, natural surroundings, and relaxed coastal lifestyle. From quiet beachside streets to homes along the Halifax River and communities farther inland, there are many ways to enjoy living here.
What's the difference between Ormond Beach and Ormond by the Sea?
Ormond Beach includes both beachside and mainland neighborhoods, while Ormond by the Sea is an unincorporated coastal community just to the north. Ormond by the Sea is known for its residential beachside setting, with the Atlantic Ocean on one side and the Halifax River on the other. Each area offers a different mix of housing, amenities, and everyday conveniences.
Can you help me explore the area before I'm ready to buy?
Absolutely. Many of our clients begin by getting to know the different communities and deciding what kind of lifestyle appeals to them. We're happy to answer questions, share local insights, and help you narrow down your options long before you're ready to make an offer.
WE'RE HERE TO HELP
Still have questions?
We'd love to hear from you. Whether you're buying, selling, or simply curious about life in Ormond Beach, we're always happy to have a conversation.
CONTACT AMY & MARKAmy & Mark Goodson
Team Goodson | Adams, Cameron & Co., Realtors
Ormond Beach, Florida

|
 |
